File IRS Form 1042-S Online
Easily report U.S.-source income paid to foreign individuals and entities with TaxZerone — an IRS-authorized e-file provider designed for accuracy, security, and bulk compliance filing.
Affordable Pricing
Starting at $2.49per form, with high-volume filing rates as low as $0.59 per form.
What Is Form 1042-S Used For?
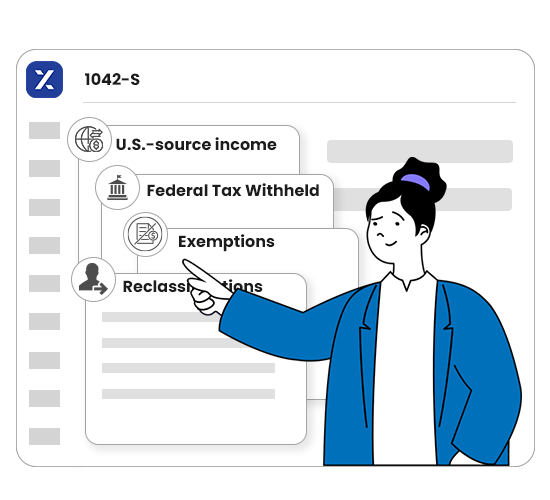
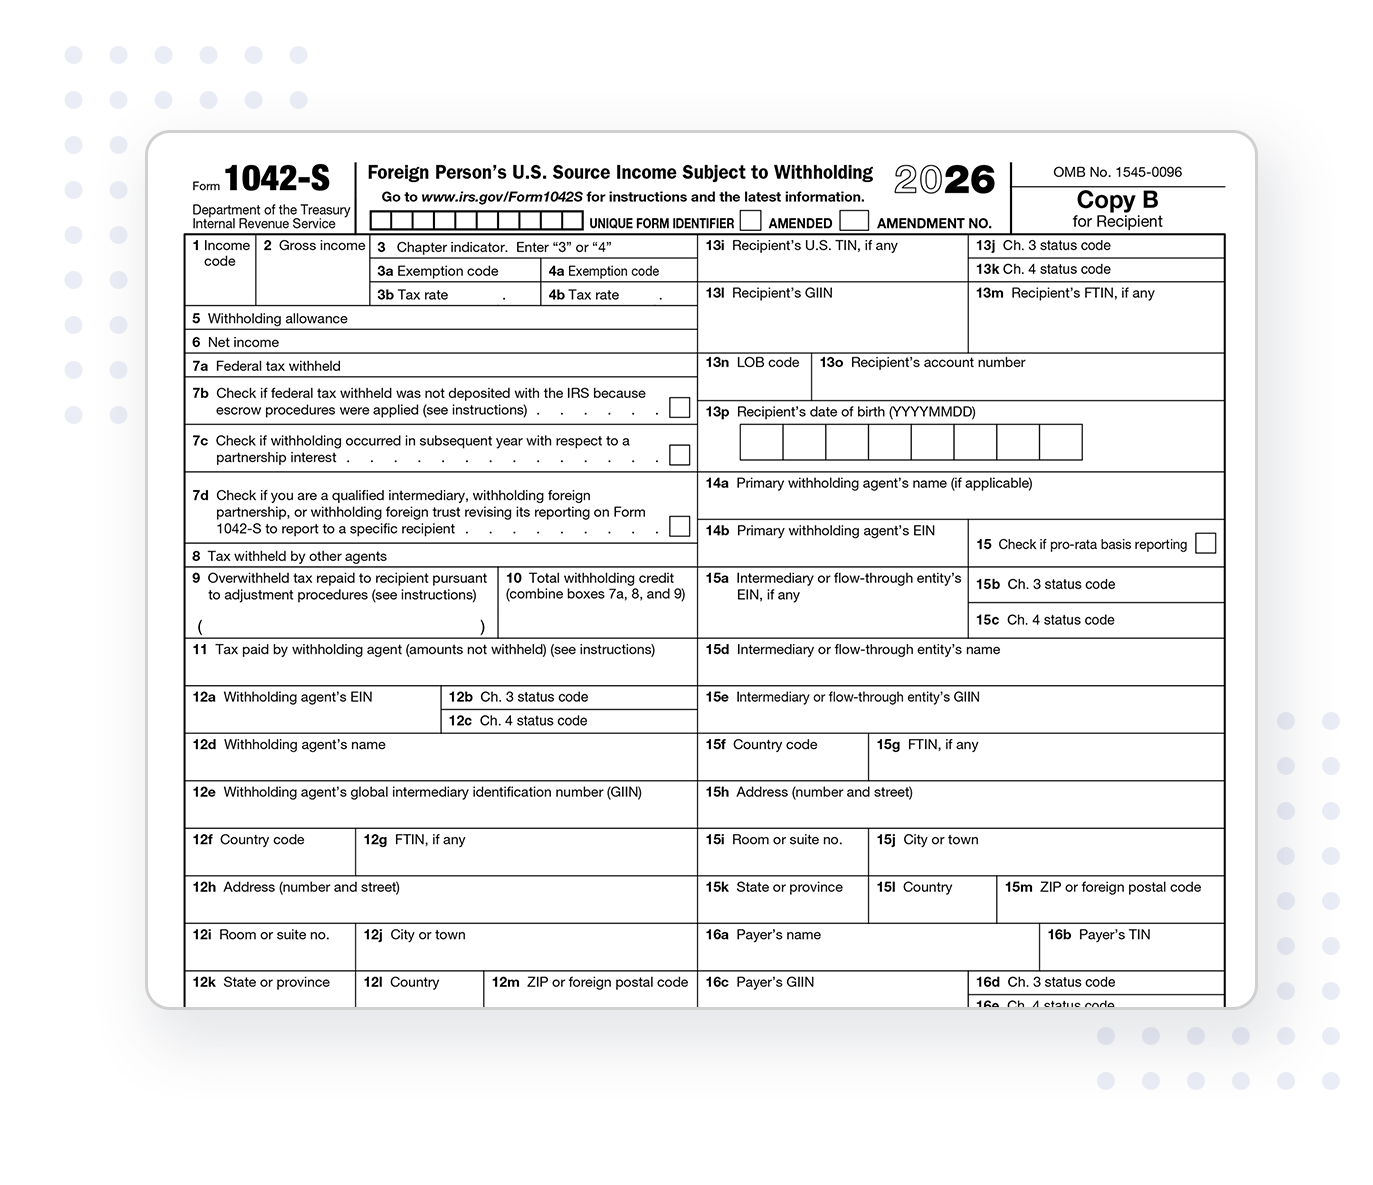
IRS Form 1042-S is used by withholding agents to report:
- U.S.-source income paid to foreign individuals, entities, or intermediaries
- The amount of federal tax withheld
- Applicable treaty benefits or exemptions
- Reclassifications, adjustments, and corrections
The IRS uses this form to ensure proper withholding on payments made to foreign persons, while recipients rely on it for tax reporting in their home countries.
Understanding U.S.-Source Income for Foreign Persons
Any payment made to a nonresident alien, foreign corporation, foreign partnership, foreign estate, or foreign trust that is considered U.S.-source income may require Form 1042-S.
Common types of reportable income include:
- Interest and dividends
- Royalties
- Scholarships & fellowships
- Compensation for services
- Rents & real estate income
- Broker proceeds
- Prizes, awards & grants
Whether the payment is taxable or exempt, the transaction must usually be reported
on Form 1042-S.
Who Must File Form 1042-S?
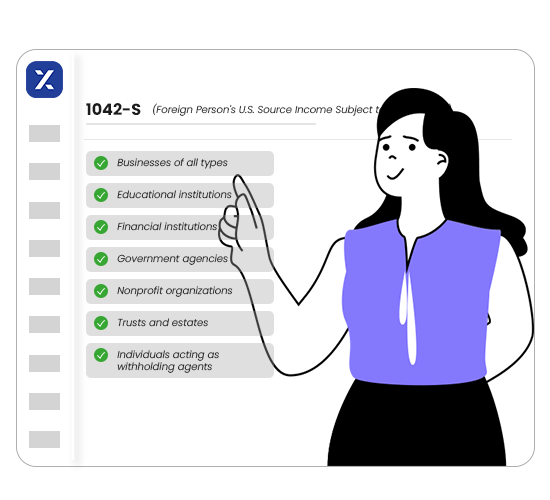
You must file Form 1042-S if you are a withholding agent who makes U.S.-source payments to foreign persons. This includes:
- Businesses of all types
- Educational institutions
- Financial institutions
- Government agencies
- Government agencies
- Nonprofit organizations
- Trusts and estates
- Individuals acting as withholding agents
A separate Form 1042-S must be filed for each recipient and each type of income paid.
Filing is required even when no tax was withheld, such as payments exempt under a tax treaty or treated as effectively connected income (ECI).
Payments made to residents of U.S. territories are generally not reportable if the beneficial owner is a U.S. citizen, national, or resident alien.
3 Easy Steps to E-file IRS Form 1042-S
With TaxZerone, the filing process is simple and intuitive.
Enter Payer & Recipient Information
Provide withholding agent details and recipient information including name, address, TIN/ITIN, and Chapter 3 or Chapter 4 status.
Report Income & Withholding
Enter the appropriate income codes, exemption codes, withholding amounts, treaty benefits, and tax rates.
Review & Transmit
Use built-in error checks to ensure accuracy, then securely transmit your form to the IRS. Instantly send recipient copies by ZeroneVault or postal mail.
Powerful Features That Simplify Your 1042-S E-filing

IRS Authorized
E-file confidently through a trusted IRS-authorized provider.
Deliver Recipient Copies
Send secure beneficiary copies through ZeroneVault or via postal mail.

Bulk Filing Support
Upload thousands of 1042-S forms at once — ideal for universities, payroll teams, financial institutions, and global businesses.

Real-Time Status Updates
Track your IRS submission every step of the way.

Affordable Pricing
Transparent pricing designed for both single filers and large enterprises.

Expert Assistance
TaxZerone’s support team provides guidance on income codes, treaty benefits, and withholding requirements.
Form 1042-S Deadlines for the 2025 Tax Year
Stay compliant with the IRS deadlines for reporting payments to foreign individuals and entities.
| Filing Requirement | Deadline |
|---|---|
| Furnish recipient copies | March 16, 2026 |
| File Form 1042-S with IRS (electronic) | March 16, 2026 |
Summary
- March 16, 2026 → Provide copies to foreign recipients
- March 16, 2026 → E-file Form 1042-S with the IRS
Running Out of Time? File for an Extension
Get additional time to file or send recipient copies by requesting an extension below.
Form 8809
Request an Extension to File Information Returns
- Need more time to file your 1042 s form? E-file Form 8809 to request an automatic 30-day extension to file 1042s Form with the IRS.
Form 15397
Request an Extension to Furnish Recipient Statements
- Need more time to send recipient copies of 1042-s form? File Form 15397 to request a one-time 30-day extension to furnish 1042s recipient statements.
File Extension in Mins
Form 1042-S Penalties
The IRS imposes penalties if you file Form 1042-S late, submit incorrect information, or fail to furnish recipient copies on time. Penalties apply per form, which can become costly for high-volume filers.
Penalties for Late Filing With the IRS
If you fail to file a correct Form 1042-S by the due date (including extensions), and no reasonable cause applies, the IRS may impose the following penalties:
- $60 per form if filed within 30 days after the due date Maximum: $683,000 per year (or $239,000 for small businesses)
- $130 per form if filed more than 30 days late but on or before August 1 Maximum: $2,049,000 per year (or $683,000 for small businesses)
- $340 per form if filed after August 1 or not filed at all Maximum: $4,098,500 per year (or $1,366,000 for small businesses)
A small business is defined as having average annual gross receipts of $5 million or less for the previous 3 tax years.
Penalties for Incorrect or Incomplete Forms
These penalties apply to errors such as missing or invalid TINs, incorrect income codes, wrong Chapter 3/4 status, incorrect treaty benefit claims, or mismatched withholding amounts.
Penalty amounts follow the same three tiers as late filing penalties.
Penalties for Failure to Furnish Recipient Copies
You must provide correct Copies B, C, and D of Form 1042-S to recipients by the required deadline. Penalties may apply separately from IRS filing penalties:
- Up to $340 per failure, with a maximum of $4,098,500 ($1,366,000 for small businesses)
- Reduced penalties apply if recipient copies are furnished by August 1, matching IRS late-filing penalty tiers.
Intentional Disregard Penalty
If the IRS determines intentional disregard of filing or furnishing requirements:
- Penalty is the greater of $680 per form or 10% of the amount that should have been reported
- No maximum limit applies
- Also applies when electronic filing is required but not completed, without a waiver or reasonable cause.
Extension to File Form 1042-S (Form 8809)
If you need more time to file Form 1042-S with the IRS, you can request an automatic extension by submitting Form 8809, Application for Extension of Time to File Information Returns.
How the 1042-S Filing Extension Works
- Filing Form 8809 provides a 30-day automatic extension to file Form 1042-S with the IRS.
- You must submit Form 8809 on or before March 15 (the original filing deadline).
- The extension applies only to filing with the IRS — it does NOT extend the deadline to furnish recipient copies, which must still be provided by March 15.
Common Errors When Filing Form 1042-S
Avoid these frequent mistakes to prevent IRS rejections:
- Incorrect income code or exemption code
- Wrong withholding rate or treaty claim
- Mismatched recipient information
- Missing Chapter 4 (FATCA) classification
- Reporting U.S. person income incorrectly
- Late submissions or incorrect tax year
How to Amend an Error on
Form 1042-S
Made a mistake? You can easily file an amendment.
To amend Form 1042-S:
- Check the “Amended” box on the form
- Update the information with the correct details
- Retransmit the amended form electronically
- Send updated recipient copies
With TaxZerone, amending Form 1042-S is simple — just update the form and resubmit. No paper forms required.
Simplify Your Form 1042-S Filing with TaxZerone
TaxZerone makes foreign income reporting fast, reliable, and stress-free:
- Built-in validations for codes, rates, and classifications
- Quick and guided filing workflow
- Simple bulk-upload functionality
- Transparent and competitive pricing
- Fully encrypted and secure e-filing
Frequently Asked Questions
What is the difference between Form 1042 and Form 1042-S?
Form 1042-S reports U.S.-source income and withholding for each foreign recipient.
Form 1042 summarizes total annual withholding activity for the withholding agent.
What information is required to e-file Form 1042-S?
You’ll need:
- Withholding agent details (name, EIN, address)
- Recipient information (name, foreign address, TIN/ITIN if applicable)
- Income codes and exemption codes
- Tax rate or treaty claim
- Federal tax withheld
- Chapter 3 or Chapter 4 status
- Any adjustments or corrections
Are treaty benefits reported on Form 1042-S?
Yes. If a tax treaty reduces or eliminates withholding, you must:
- Enter the treaty country
- Report the applicable treaty article
- Use the correct exemption code
- Apply the correct reduced tax rate
Do I need to file Form 1042-S if no tax was withheld?
Yes. Even if withholding is 0%, you must file Form 1042-S if the payment is:
- U.S.-source
- Made to a foreign person
- Reportable under IRS rules
Can I file multiple 1042-S forms electronically?
Absolutely. TaxZerone supports bulk filing via spreadsheet upload, allowing organizations to submit hundreds or thousands of forms efficiently.
1042-s and/or 1099
Form 1099 and Form 1042-S are IRS information returns used to report non-employee income, but they apply to completely different tax statuses. Form 1099 reports income paid to U.S. persons, while Form 1042-S reports U.S.-source income paid to foreign persons (non-residents), often involving tax withholding.
Core Differences
| Key Information | Form 1042-S | Form 1099 |
|---|---|---|
| Recipient Status | Issued to foreign individuals, foreign entities, or non-residents (collected via Form W-8BEN or W-8BEN-E). | Issued to U.S. citizens, resident aliens, and domestic entities |
| Payment Threshold | Has no minimum threshold; you must file for any reportable amount. | Generally, requires a minimum threshold of $600 in payments (varies slightly by specific 1099 type). |
| Tax Withholding | Commonly tracks standard or tax-treaty-reduced withholding rates (up to 30% gross tax withheld). | Usually does not involve direct tax withholding unless subject to backup withholding. |
| Filing Threshold | Due to recipients and the IRS by March 15. | Due to recipients and the IRS by January 31. |
1042 vs 1042-s
The main difference between IRS Form 1042 and Form 1042-S is that Form 1042 is an annual summary return for the organization, while Form 1042-S is a detail form issued for each individual foreign recipient.
| Filing Requirements | Form 1042 | Form 1042-S |
|---|---|---|
| Purpose | Form 1099 reconciles total tax withheld from U.S.-source income paid to foreign persons | Form 1042-S details specific individual payments, income types, and tax withheld for a specific person. |
| Volume | An organization files only one Form 1042 per year. | An organization files one Form 1042-S for each foreign recipient or transaction. |
| Recipients | Form 1042 is filed only with the Internal Revenue Service (IRS). | Form 1042-S is filed with the IRS and furnished to the foreign recipient (such as a nonresident alien, foreign corporation, or foreign partnership |
| Filer | Withholding agent responsible for withholding and reporting the tax. | Withholding agent responsible for reporting the payment and withholding. |
| Deadlines | Generally due March 15 following the calendar year. | Generally due March 15 following the calendar year. |
How do I fill out Form 1042-S correctly?
To complete Form 1042-S, enter the withholding agent's information, recipient details, income code, gross income, and any federal tax withheld. Make sure the recipient's name, address, tax identification number, and applicable withholding rate are accurate. Review the form against the IRS Form 1042-S instructions before filing and provide a copy to the recipient when required.