Form W-2 Instructions
Last updated:
-by Alexia Zepeda | TaxZerone
Form W-2 at a Glance
- Form W-2 reports an employee's annual wages, tips, and federal income, Social Security, and Medicare taxes withheld during the tax year.
- 2026 reporting threshold change: The reporting threshold increased from $600 to $2,000 for certain wages paid in 2026 when no federal income tax, Social Security tax, or Medicare tax was withheld. Employers must still file Form W-2 when applicable taxes were withheld, regardless of the amount paid.
- Employers must file Form W-2 with the Social Security Administration (SSA) and provide copies to their employees by February 1, 2027, for Tax Year 2026.
- This article explains how to complete Form W-2 box by box, including employer and employee information, wages, tax withholdings, Social Security and Medicare contributions, tips, dependent care benefits, retirement contributions, new Box 12 codes, Box 13 checkboxes, Box 14 reporting, and state and local taxes.
- For 2026, employers must also report qualified cash tips and qualified overtime compensation using new Box 12 codes. Box 14 has been divided into Box 14a (Other) and Box 14b (Treasury Tipped Occupation Codes).
- Late filing penalties for Form W-2 range from $60 to $690 per return, depending on the filing delay and whether the failure was intentional.
- If you need additional time to file Form W-2 with the SSA, you can request a 30-day extension using Form 8809. Extensions are not automatic and are generally granted only for extraordinary circumstances or catastrophes.
Who Must File Form W-2?
Employers are responsible for preparing and filing Form W-2 for employees who receive reportable wages, tips, or other compensation.
For wages paid in 2026, the general reporting threshold has increased from $600 to $2,000 when no federal income tax, Social Security tax, or Medicare tax was withheld. If any of these taxes were withheld, the reporting requirement can apply regardless of the amount paid.
Employers use Form W-2 to report two important types of information:
- Employee income and taxes withheld: Reports wages, bonuses, tips, and federal income, Social Security, and Medicare taxes withheld.
- Social Security earnings: Helps the SSA maintain employees' earnings records and calculate their future Social Security benefits.
Employees who receive reportable wages or compensation must generally receive a Form W-2. This includes full-time, part-time, and temporary employees.
When Is Form W-2 Due for 2026?
Employers must file Form W-2 with the SSA and furnish employee copies by February 1, 2027, for Tax Year 2026.
| Filing requirement | Due date |
|---|---|
| File Form W-2 with the SSA | February 1, 2027 |
| Provide employee copies | February 1, 2027 |
| File electronically or on paper | February 1, 2027 |
👉 For more information about filing deadlines, refer to our W-2 due dates.
E-file today and avoid the deadline rush!
Skip the last-minute scramble and e-file your W-2s now
Form W-2 Penalties for 2026
Employers who fail to file accurate Forms W-2 or furnish employee copies on time may face penalties. The penalty depends on how late the correct form is filed.
The following penalty amounts apply to Forms W-2 due in 2027:
| Filing delay | Penalty per return | Maximum for small businesses | Maximum for large businesses |
|---|---|---|---|
| Within 30 days | $60 | $244,500 | $698,500 |
| 31 days late through August 1 | $130 | $698,500 | $2,095,500 |
| After August 1 or not filed | $340 | $1,397,000 | $4,191,500 |
| Intentional disregard | At least $690 | No maximum | No maximum |
Small businesses generally have average annual gross receipts of $5 million or less during the applicable three-year period.
Don't risk penalties!
Be proactive! E-file your W-2 forms ahead of the deadline.
Form W-2 Instructions: How to Fill Out Form W-2 for 2026
Let's review the box-by-box instructions for completing Form W-2 for Tax Year 2026.
Employer information
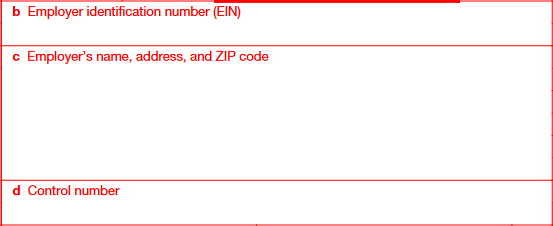
- Box b: Enter the business EIN
- Box c: Enter the Employer's name, address, and ZIP code
- Box d: Enter the control number. It's a unique number, used by many employers to internally track and organize their W-2 forms. It's not required by the IRS
Employee information
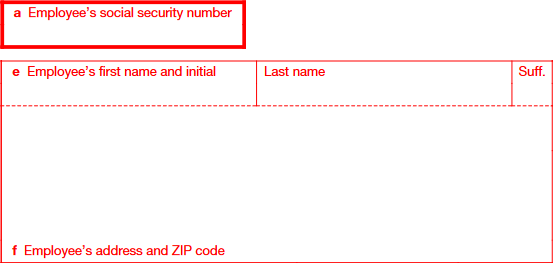
- Box a: Enter the employee's SSN
- Box e: Enter the employee's first name and initial, last name, and suffix in the respective fields
- Box f: Enter the employee's address and zip code
Box 1: Wages, tips, other compensation
Box 1 should include the total wages, tips, bonuses, prizes, and other taxable compensation paid to the employee during the year. DO NOT include pre-tax deductions like 401(k) contributions. Key things to include:
- Total wages, bonuses, prizes, and awards
- Noncash fringe benefits
- Reported tips
- Reimbursed employee business expenses
- Insurance premiums for 2% S-corp shareholders
- Employee contributions to HSAs and MSAs
- Group-term life insurance over $50,000
- Non-job related educational assistance
- Employer-paid social security and Medicare taxes
- Roth 401(k) contributions
- Nonqualified deferred compensation distributions
- Amounts includible under section 457(f)
- Split-dollar life insurance payments Insurance premiums for 2% S-corp shareholders
- HSA contributions if taxable to employee
- 409A deferred comp no longer subject to risk of forfeiture
- Nonqualified moving expenses and reimbursements
- Payments to employees on active military duty
- Other taxable compensation like scholarships
Box 2: Federal income tax withheld
Report the total federal income tax withheld from the employee's wages for the year. This includes:
- Federal income tax withholding
- 20% excise tax withheld on excess golden parachute payments.
Box 3: Social security wages
Report the employee's total wages subject to Social Security tax, excluding Social Security tips reported separately in Box 7.
- Wages paid before deductions
- Noncash payments
- Reimbursed employee expenses
- Elective deferrals to retirement plans
- Designated Roth contributions
- Deferrals under section 457(f) and nonqualified plans
- Signing bonuses
- Group-term life insurance over $50K
- Accident/health insurance for 2% S-corp shareholders
- Contributions to MSAs and HSAs
- SIMPLE contributions
- Adoption benefits
The combined amount in Boxes 3 and 7 cannot exceed the 2026 Social Security wage base of $184,500.
If you paid the employee share of social security tax, report the gross amount.
Box 4: Social security tax withheld
Enter the total employee Social Security tax withheld from wages and tips.
- Include only the employee's share, not the employer's share.
- The Social Security tax rate for employees is 6.2%.
- The maximum employee Social Security tax for 2026 is $11,439 ($184,500 × 6.2%).
Box 5: Medicare wages and tips
Report total Medicare wages and tips. This includes:
- All wages and tips subject to social security tax (boxes 3 and 7)
- There is no wage base limit for Medicare tax
- Enter tips that employees reported even if you couldn't collect Medicare tax on them
If you paid the employee Medicare tax, report the gross amount of wages.
For government employers with employees who pay only Medicare tax, enter Medicare wages in box 5
Box 6: Medicare tax withheld
Enter the total employee Medicare tax withheld during 2026.
- Include the employee's regular Medicare tax.
- Include any Additional Medicare Tax withheld.
- Do not include the employer's share of Medicare tax.
The regular employee Medicare tax rate is 1.45%. An additional 0.9% withholding applies to wages exceeding $200,000 paid by an employer to an employee during the calendar year.
Box 7: Social security tips
Report all Social Security tips the employee reported to the employer during the year.
- Include all cash and charges reported by the employee.
- Report the same tips in Box 1, as applicable.
- Include reported tips in Box 5 for Medicare wages and tips.
- The combined total of Boxes 3 and 7 cannot exceed $184,500 for 2026.
Box 8: Allocated tips
Report allocated tips for employees at large food/beverage establishments.
- Only includes tips allocated by the employer, not reported directly by the employee
- Do not include allocated tips in boxes 1, 3, 5 or 7
- Allocated tips are reported on Form 8027
Box 10: Dependent care benefits
Report total dependent care benefits provided to the employee under a dependent care assistance program (section 129).
This include:
- Fair market value of employer-sponsored daycare
- Amounts paid or reimbursed for dependent care under a section 125 cafeteria plan
- Value of in-kind benefits provided by the employer
- Amounts paid directly to a daycare facility
- Report all amounts paid, including those above the $5,000 exclusion.
Also include any dependent care benefits over the exclusion limit in boxes 1, 3, and 5 as wages.
Box 11: Nonqualified plans
Report distributions to the employee from a nonqualified deferred compensation plan or nongovernmental section 457(b) plan.
- This helps the SSA determine if any part of box 1, 3, or 5 was earned in a prior year.
- Also report these distributions in box 1.
- Only make one entry in box 11
- Do not report governmental 457(b) plan distributions here. Use Form 1099-R instead.
- Report deferrals that are no longer subject to risk of forfeiture in boxes 3 and 5, not box 11.
- Do not report current year deferrals or deferrals already in boxes 3/5.
Box 12: Codes
Report codes and amounts for all applicable items listed below. The codes do not correspond to boxes 12a–12d on Form W-2.
- Use box 12 to report any items A through II
- Do not report section 414(h)(2) govt plan contributions here — use box 14 instead
- Also use box 14 for other information like union dues, uniform payments, etc.
For Tax Year 2026, three new codes have been introduced: TA, TP, and TT.
| Code | Description |
|---|---|
| A | Uncollected Social Security or RRTA tax on tips |
| B | Uncollected Medicare tax on tips |
| C | Taxable cost of group-term life insurance over $50,000 |
| D | Elective deferrals under a Section 401(k) plan |
| E | Elective deferrals under 409A nonqualified plan |
| F | Elective deferrals to 408(k)(6) SARSEP plan |
| G | Elective deferrals and employer contributions to a Section 457(b) plan |
| H | Elective deferrals under a Section 501(c)(18)(D) plan |
| J | Nontaxable sick pay |
| K | 20% excise tax on excess golden parachute payments |
| L | Substantiated employee business expense reimbursements |
| M | Uncollected Social Security or RRTA tax on group-term life insurance over $50,000 for former employees |
| N | Uncollected Medicare or RRTA Medicare tax on group-term life insurance over $50,000 for former employees |
| P | Excludable moving expense reimbursements paid directly to eligible military or intelligence community members |
| Q | Nontaxable combat pay |
| R | Employer contributions to an Archer MSA |
| S | Employee salary reduction contributions under a SIMPLE plan |
| T | Adoption benefits |
| V | Income from the exercise of nonstatutory stock option(s) |
| W | Employer contributions to a Health Savings Account (HSA) |
| Y | Deferrals under a Section 409A nonqualified deferred compensation plan |
| Z | Income under a nonqualified deferred compensation plan that fails Section 409A requirements |
| AA | Designated Roth contributions under a Section 401(k) plan |
| BB | Designated Roth contributions under a Section 403(b) plan |
| DD | Cost of employer-sponsored health coverage |
| EE | Designated Roth contributions under a governmental Section 457(b) plan |
| FF | Permitted benefits under a qualified small employer health reimbursement arrangement |
| GG | Income from qualified equity grants under Section 83(i) |
| HH | Aggregate deferrals under Section 83(i) elections as the close of the calendar year |
| II | Medicaid waiver payments excluded from gross income under Notice 2014-7 |
| TA | Employer contributions under a section 128 Trump account contribution program paid to a Trump account of an employee or a dependent of an employee |
| TP | Total amount of cash tips reported to the employer |
| TT | Total amount of qualified overtime compensation |
Important 2026 updates to Box 12:
- Code TA: Reports eligible employer contributions to Trump accounts beginning July 4, 2026.
- Code TP: Reports the total cash tips reported to the employer.
- Code TT: Reports qualified overtime compensation. Generally, only the premium portion above the employee's regular rate is included, such as the additional half of time-and-a-half pay.
These codes help employees identify qualifying amounts when calculating applicable deductions on their individual income tax returns.
Box 13: Checkboxes
Check all boxes that apply:
Statutory employee:
- Check this if the worker is a statutory employee (not a common-law employee)
- Applies to certain drivers, insurance agents, home workers, traveling salespeople
- Statutory employees have social security/Medicare tax but no income tax withholding
Retirement plan:
- Check this if the employee was covered by a retirement plan such as:
- 401(k), 403(b), SEP, or SIMPLE plans
- Governmental plans
- Section 501(c)(18) trusts
- Generally applies if employee was eligible to participate or had contributions
- Do not check for nonqualified or 457(b) plans
Third-party sick pay:
- Check this only if reporting sick pay paid by a third party
- Applies if you are the third party payer or the employer reporting third party sick pay
Box 14a: Other
The 2026 Form W-2 separates the previous Box 14 into two fields. Use Box 14a to report other information that employers need to communicate to employees.
Examples include:
- State disability insurance taxes
- Union dues
- Uniform payments
- Health insurance premiums
- Minister's housing allowance
- Certain pension plan contributions
- Other applicable employee information
Box 14b: Treasury Tipped Occupation Codes
This is a new reporting field on the 2026 Form W-2.
Use Box 14b to report the Treasury Tipped Occupation Code(s) associated with the employee's qualified cash tips reported under Box 12, Code TP.
- Enter up to two applicable occupation codes.
- If tips were earned in multiple occupations, report the applicable codes according to IRS instructions.
- If tips were received in a nonqualifying occupation, enter code 000 as one of the occupation codes.
Boxes 15–20: State and Local Income Tax Information

Use these boxes to report the employee's state and local income tax details.
- Box 15: Enter the two-letter state abbreviation and employer state ID number.
- Box 16: Report state wages.
- Box 17: Report state income tax withheld.
- Box 18: Report local wages and tips.
- Box 19: Report local income tax withheld.
- Box 20: Enter the name of the locality.
You can report information for up to two states and two localities on one Form W-2. If you need to report additional state or local information, prepare another Form W-2.
How to File Form W-2 for 2026?
Employers can file Form W-2 electronically or by paper. Electronic filing is a convenient option for businesses that need to submit multiple employee wage statements.
Form W-2 E-filing (recommended)
The IRS recommends e-filing your W-2s for a faster and simpler experience. Plus, you'll get instant notifications when they're processed.
It's that quick and easy! Choose e-filing for a smooth and efficient W2 online filing experience.
Paper filing
If you choose to file Form W-2 on paper, follow these steps:
- Obtain the official 2026 Form W-2 and Form W-3.
- Enter the employer's and employee's information.
- Report wages, tips, and applicable tax withholdings.
- Send Copy A of Form W-2 along with Form W-3 to the SSA.
- Provide the required employee copies by January 31st of the following calendar year.
Important notes for paper filing:
- Use the correct Form W-2 for Tax Year 2026.
- Ensure all entries are accurate and legible.
- Send employee copies separately.
- Allow sufficient mailing time to meet the deadline.
Where to send Form W-2 - Mailing address
Send Form W-2 and W-3 to the address below:
| By U. S. Postal Service | Social Security Administration Direct Operations Center Wilkes-Barre, PA 18769-0001 |
| By Private Delivery Service (FedEx, UPS, etc.) | Social Security Administration Direct Operations Center Attn: W-2 Process 1150 E. Mountain Drive Wilkes-Barre, PA 18702-7997 |
Note: Do not send Forms W-2 and W-3 to the IRS. They must be submitted to the SSA.
How to E-file Form W-2 for 2026?
E-filing Form W-2 with TaxZerone involves three simple steps. Before starting, gather your employer information, employee details, wage information, and tax withholding amounts.
Information Required to File Form W-2
Keep the following information ready:
- Employer information: Business name, address, and EIN.
- Employee information: Employee name, address, and SSN.
- Wage information: Salaries, bonuses, tips, and other taxable compensation.
- Tax information: Federal income tax, Social Security tax, and Medicare tax withheld.
- Additional information: Retirement contributions, dependent care benefits, and applicable state and local tax details.
Once you have these details, follow the steps below.
- Step 1: Fill Out Form W-2
Enter your employer and employee information, report wages and taxes withheld, and complete the applicable boxes. - Step 2: Review and Transmit the Return
Review the information for accuracy, correct any identified errors, and submit your W-2 forms electronically to the SSA. - Step 3: Deliver Employee Copies
After filing, provide the required employee copies through a secure delivery method.
E-file Form W-2 with TaxZerone
Simplify your 2026 W-2 filing process with TaxZerone. Prepare employee wage statements, review filing information, and submit your returns electronically through one platform.
With TaxZerone, you can:
- Automated form validation: Identify common errors before submitting your W-2 forms.
- Bulk filing: Upload multiple W-2 forms using supported file formats to simplify large-volume filing.
- Secure recipient copies: Deliver employee statements through ZeroneVault, where employees can securely access, download, and print their copies.
- Convenient filing: Prepare and submit W-2 forms online without managing paper documents.
- Filing status tracking: Follow your submission status and receive filing updates.
- Affordable pricing: Start filing at $2.49 per form, with bulk filing prices as low as $0.59 per form.
E-file W2 Form with TaxZerone
File your W2 easily with TaxZerone, starting at just $2.49 per form, with bulk filing options as low as $0.59 Per form.
You’ll also receive instant updates on your filing status once it’s processed.